

The minutes of the Reserve Bank's November meeting were released on Tuesday 17 November, and they are a more interesting document than the decision they explain. On 3 November the Board had lifted the cash rate to 4.85 per cent, its fifth rise of the year, by six votes to three,[1] and at the time that was the whole story. The minutes show a board that agreed on the facts and disagreed about what to fear, and I think the three who voted to hold made a serious argument, one that deserves better than the "Gang of 3" label it has been given.
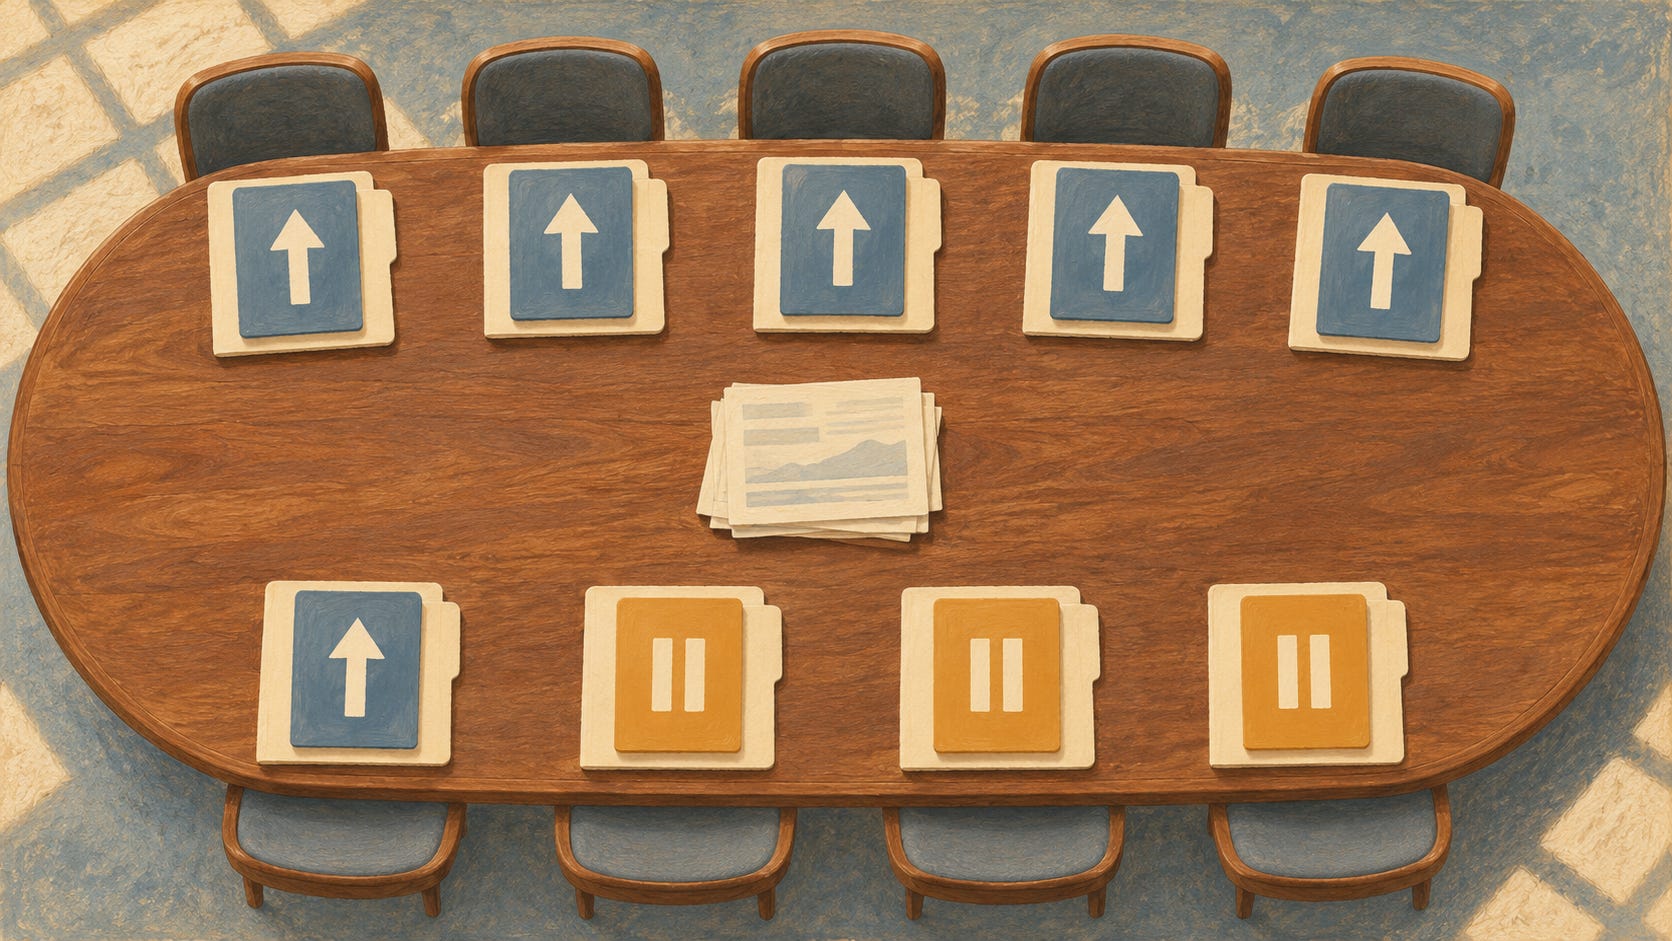
Inflation in the September quarter had come in stronger than the Bank expected in August, and it was broadly based, with market services inflation noticeably stronger than forecast and fuel making the largest contribution to the surprise in the headline figure. The staff forecasts had been revised a long way: headline and underlying inflation are now expected to stay above 3 per cent until late 2027, and to reach the middle of the 2 – 3 per cent target range only in mid-2028, about three quarters later than the Bank was saying in August.[2] The economy, meanwhile, was plainly slowing, housing prices were down almost 5 per cent from their March peak, and the unemployment rate had risen by more than anyone had expected. Both sides of the table had those same numbers in front of them, and Governor Michele Bullock said on the day that the difference came down to weighting, with the members who favoured a hold putting more weight on the downside risks and the members who favoured a rise putting more on the upside.[3]
The six started from the view that the inflation problem is more domestic than the fuel numbers make it look. Market services are the category most sensitive to conditions at home, and their inflation had risen in the September quarter, while unit labour costs kept growing strongly and the Bank’s liaison contacts kept reporting cost pressures across most industries. Put those together and the staff had concluded that capacity pressures through 2026 had been greater than they had previously assessed, which is why the estimate of the unemployment rate consistent with stable inflation had itself been revised up. Does that prove the economy was running too hot? No. But it is the kind of evidence that, if you accept it, makes the next round of cost increases easier for firms to pass on, whatever set them off, and a central bank that waits for proof has usually waited too long.
The forecasts also rest on an assumption that deserves more attention than it has had. Oil prices are assumed to fall by around US$30 a barrel over the coming two years, and the minutes are frank that this requires some degree of resolution of the conflict in the Middle East, without which the central forecast is too low rather than too high. On top of that, some measures of inflation expectations had risen, and the majority worried that another year of inflation above 3 per cent, with a very high headline number expected for October, would start to change how firms set prices and how workers bargain. Surely that settles it, I hear you ask. If expectations go, everything goes. Yes, that is the strongest part of their case, and it is a real risk, particularly for people on lower incomes who have no inflation-linked support to fall back on. But the evidence for it, on the minutes’ own account, was new or imprecise, and the established market measures of expectations were still well anchored, which is exactly where the other three started.
And so the six voted to raise a rate they described, in the same document, as “not clearly sufficient”[4] to do the job. Part of the problem is the neutral rate, the level at which policy neither stimulates nor restrains, because estimates of it have drifted up over recent years, so a cash rate that would once have bitten hard may now be biting less. The rise was therefore bought for assurance, to make sure financial conditions really were restrictive enough to bring the economy back to balance, and the majority judged the risk of doing too little to be the larger one. That is a defensible judgement. It is also, when you read it slowly, an extraordinary one, because it amounts to tightening policy while conceding that nobody at the table could say how much tightening was already in place.
The three began with the 100 basis points of tightening the Board had already delivered this year (in February, March, May and September), and with the plain fact that monetary policy works slowly, taking a year or more to flow through to spending and prices, on the Governor’s own account at her press conference. The full effect of the September rise had barely begun to show in the data by November, let alone the three rises before it, and their argument was a timing argument. Further tightening might still prove necessary, they accepted, but there was no need to make that judgement at this meeting, six weeks after the last rise, when another meeting was coming in December and the evidence was about to get better. Waiting was not doing nothing. Waiting was letting the medicine already prescribed finish working before prescribing more.
What they feared was the other error. Unemployment had risen by half a percentage point in the six months before the meeting, which was larger than expected, and the housing market was in a cyclical downturn that could easily drag harder on activity than the historical relationships in the staff forecasts allow for, because turnover, construction and household wealth all feed on each other. New housing lending had fallen 15.5 per cent in the September quarter, with investor lending down by almost a third.[4] These members said the economy might be near the point of entering a “materially sharper downturn”, and they pointed to what that would cost in unemployment. A rate rise can be reversed in an afternoon. A year of lost work cannot.
They also thought the inflation risks were closer to balanced than the staff had assessed, and they had evidence of their own. The monthly pace of market services inflation had slowed through the September quarter, wages growth had been stable for a year, which is hard to square with a labour market that is supposed to be tight, and business credit and household savings buffers told a mixed story rather than a clear one. None of that proves the staff wrong, and the three did not claim it did. It does mean the picture the majority acted on was a judgement laid over uncertain estimates, and judgements laid over uncertain estimates are exactly where reasonable boards split.
So the decision came down to a choice between two mistakes, both of them invisible at the moment of choosing. Do too little and inflation expectations take root, after which the correction is longer and harder and falls, as the minutes themselves note, most heavily on Australians on lower incomes. Do too much and you deepen a downturn that was already under way, and the bill arrives in jobs held by people who had nothing to do with causing the inflation. I spent decades watching organisations make decisions on numbers like these, and the pattern is familiar, because the neutral rate is an estimate, the unemployment rate consistent with stable inflation is an estimate, and capacity pressure is inferred from the very inflation it is meant to explain. When the dials cannot be read directly, honest people read them differently, and the honest output of the process is a split vote.
We know any of this only because unattributed votes have been published since last year, and that change deserves more credit than it gets. September’s rise was unanimous and November’s was not, and under the old arrangements both decisions would have arrived in identical clothing, as a single statement in a single institutional voice, giving an impression of settled certainty that the November meeting had not in fact produced. A board that publishes its disagreements is easier to hold to account than one that hides them, because in a few months we will be able to say which judgement the data supported and which it did not.
CommBank’s Belinda Allen read the minutes as pointing to a pause, judging that December “will not be a live meeting” after two back-to-back rises, with February the next meeting at which a rise could be seriously considered, and then only if inflation surprises materially to the upside.[5] Before the Board meets on 7 and 8 December it will have October inflation, due on 24 November, and September quarter GDP, due on 2 December, and on the evidence of these minutes neither number is likely to end the argument, because the argument was never really about one month’s number. It was about how much weight to put on risks that point in opposite directions.
Switzer’s framing was that the three might be right but we will not know until March, so let us make that test concrete, because by March we will have the December quarter inflation result and two more rounds of labour force figures. What would prove the six right? Market services inflation still strong in the December quarter, the measures of expectations that lifted lifting again, and household spending holding up as it has so far, which together would say that capacity really was tighter than anyone wanted to believe. And what would prove the three right? Unemployment rising faster than the Bank’s own path (4.7 per cent by December, on its way to a little over 5 per cent by the end of 2028), a housing downturn that deepens past the forecasts, and that slower monthly pace in market services turning out to have been the signal. One of those two sets of numbers is coming, and the forecasts cannot tell us which, because the forecasts were written by the people who have just disagreed about them.
Since the minutes were released, the first number has arrived. The October labour force figures, released on 19 November, put unemployment at 4.9 per cent in seasonally adjusted terms, up 0.1 percentage point on the Bureau’s unrounded figures, with employment down 43,500.[6] That is already above the 4.7 per cent the Bank had pencilled in for December. One month does not settle the test set out above, but the first number since the decision points the way the three feared.
A dissent kept on the public record is a receipt. It shows how uncertain the decision was at the moment it was made, and it stops anyone rewriting that uncertainty later, whichever way the numbers break. Six members voted for the risk they could see. Three voted for the risk that had not arrived yet. March will tell us which risk was real.
Sources:
[1] Reserve Bank of Australia, “Statement by the Monetary Policy Board: Monetary Policy Decision”, Media Release 2026-30, 3 November 2026. https://www.rba.gov.au/media-releases/2026/mr-26-30.html
[2] Reserve Bank of Australia, Statement on Monetary Policy – November 2026, Overview and forecast table. https://www.rba.gov.au/publications/smp/2026/nov/overview.html
[3] Reserve Bank of Australia, “Media Conference: Monetary Policy Decision – 3 November 2026”, transcript. https://www.rba.gov.au/speeches/2026/mc-gov-2026-11-03.html
[4] Reserve Bank of Australia, “Minutes of the Monetary Policy Board Meeting, 2–3 November 2026”, released 17 November 2026. https://www.rba.gov.au/monetary-policy/rba-board-minutes/2026/2026-11-03.html
[5] Belinda Allen (Commonwealth Bank), “RBA pause increasingly likely after November’s split vote”, CommBank Newsroom, 17 November 2026. https://www.commbank.com.au/articles/newsroom/2026/11/rba-rate-pause-split-vote-december-2026.html
[6] Australian Bureau of Statistics, Labour Force, Australia, October 2026, released 19 November 2026. https://www.abs.gov.au/statistics/labour/employment-and-unemployment/labour-force-australia/oct-2026
This article responds to Peter Switzer, “Did the RBA’s ‘Gang of 3’ get it right on Cup Day?”, Switzer Daily, 18 November 2026, https://switzer.com.au/did-the-rbas-gang-of-3-get-it-right-on-cup-day/
The decision, the forecasts and both sides of the argument are taken from the RBA’s own statement, Statement on Monetary Policy and minutes, as cited above.